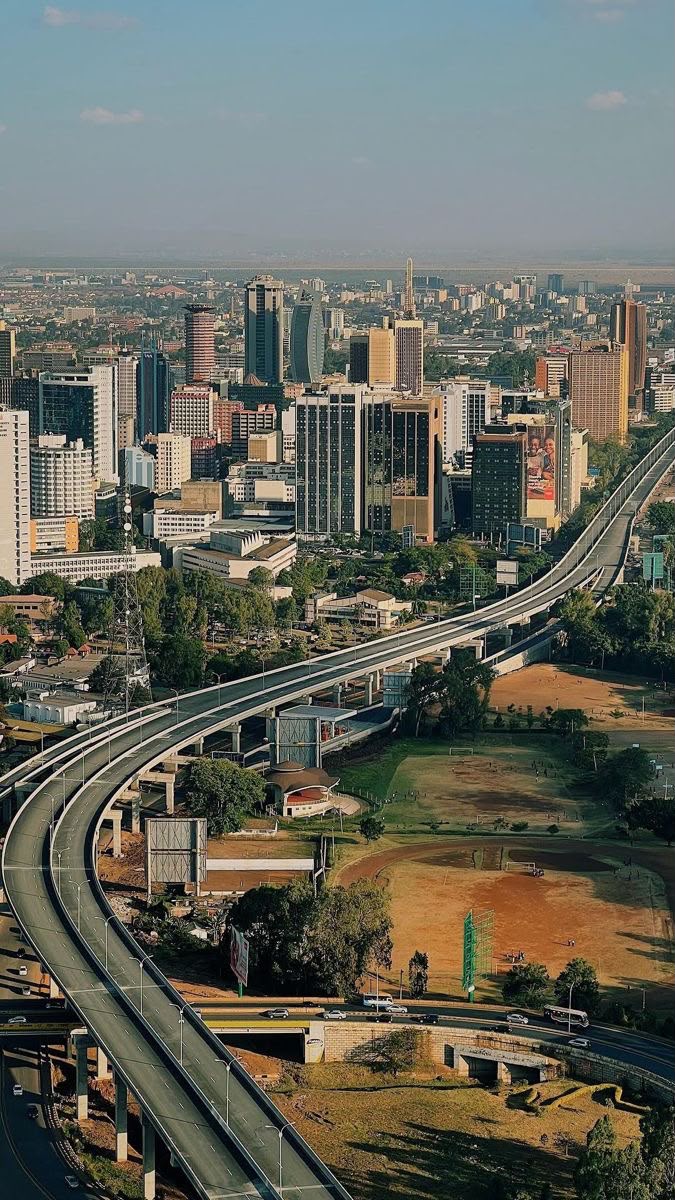
Ask two different property investors how Kenya's real estate market is doing in 2026 and you might get two completely different answers — and both of them could be right.
If you own an apartment in Westlands or parts of Kilimani, the story right now is correction. If you bought a plot in Juja or Kitengela three years ago, the story is a genuinely strong run-up in value. Same country, same year, dramatically different trend lines. Here's what's actually behind the split.
The Numbers Behind the Divide
Nationally, property prices have grown around 7.8% — a healthy-sounding headline figure. But that average is hiding a lot. Nairobi's prime suburbs are correcting by roughly 7–11%, driven largely by an oversupply of apartments in specific sub-markets: Westlands, Upper Hill, and parts of Kilimani in particular. Meanwhile, satellite towns around the capital have been posting growth closer to 15%. National rental yields sit at around 7.4%, but that number, too, varies wildly depending on which side of the divide a property sits on.
Why Nairobi's Prime Apartment Segment Is Struggling
This isn't really a demand collapse — it's a supply story. Developers spent the last several years building aggressively in a handful of fashionable Nairobi neighbourhoods, and in some of those pockets, supply has simply outpaced the number of tenants and buyers willing (or able) to pay premium prices. Add rents that have been climbing faster than incomes in some of these same areas, and you get a genuine affordability ceiling for the segment — buyers and tenants who could once stretch for a Westlands or Kilimani apartment are increasingly looking elsewhere.
Why Satellite Towns Are Winning
Meanwhile, places like Juja, Kitengela, Ruiru, and similar commuter towns have been quietly benefiting from a few converging forces:
- Road and connectivity upgrades. Improved bypasses and commuter transport links have made it genuinely feasible to live outside the city core and still commute to work, which wasn't nearly as practical a decade ago.
- Price accessibility. Entry prices in towns like Juja start from around KSh 1.2 million for houses, with rents from about KSh 2,500 — figures that are simply out of reach in central Nairobi.
- A large captive tenant base. University towns in particular — Juja is a good example, given its proximity to JKUAT — support strong rental demand from students, with reported yields in the 9–15% range in some pockets.
- A shift in what buyers actually want. Beyond raw affordability, buyers increasingly want security, green space, and a sense of community — things that are often easier to deliver in a purpose-built satellite-town estate than in a dense, older, central neighbourhood.
Land price growth in these areas is reportedly slowing even as infrastructure keeps expanding, which suggests the easiest gains in some satellite towns may already be behind early movers — though the towns riding genuinely new infrastructure corridors likely still have room to run.
The Diaspora Factor Nobody Should Ignore
One of the biggest forces quietly reshaping this whole market is money from Kenyans living abroad. Diaspora remittances hit a record USD 5.08 billion in the twelve months to June 2025, and the Central Bank of Kenya projects that figure climbing to around USD 5.24 billion in 2026. A meaningful share of that money flows straight into property, making the diaspora one of the single most important demand drivers in the market right now.
What's notable is how diaspora buyers have changed over the past few years. Compared to five years ago, they're now:
- More data-driven and due-diligence-focused before committing to a purchase.
- Increasingly favouring completed units over off-plan developments, specifically to reduce construction risk.
- Demanding professional property management rather than relying on relatives to manage a unit informally.
- More tax-compliance-aware, across both Kenyan and their country of residence's tax obligations.
That shift toward caution is worth sitting with. It's not that diaspora investors have lost interest in Kenyan property — remittance volumes say the opposite — it's that they're deploying that money more carefully than they used to.
Off-Plan Is Still Working — For Now
Despite the diaspora's growing preference for completed units, off-plan property remains a major entry point for local investors, and the numbers explain why. An analysis of eight prime off-plan developments found an average return of roughly 18% in 2025 — driven by developer discounts and instalment payment structures that create returns most other accessible investment vehicles in Kenya simply can't match. The catch is real, though: developer delays, quality shortfalls, and outright fraud remain genuine risks. Verifying a developer's track record and confirming title status through the Ardhisasa platform before signing anything isn't optional due diligence anymore — it's the baseline.
Short-Term Rentals Are Their Own Micro-Market
Worth a separate mention: Nairobi's serviced and short-let apartment scene has kept expanding, with Westlands alone accounting for over 40% of the city's total serviced apartment market. Furnished units in premium suburbs can pull in noticeably higher rental income than an equivalent unfurnished long-term let — but the honest caveat here is that the real determinant of success isn't the yield headline, it's management quality. A poorly managed short-let unit underperforms a well-managed long-term rental almost every time.
What This Split Market Means for You
If you're weighing where to put money into Kenyan property in 2026, the blanket statement "Nairobi property is a good investment" doesn't really hold up as useful advice anymore. What matters is:
- Location selectivity over city-level generalisation. A blanket "Nairobi is booming" or "Nairobi is correcting" framing misses the sub-market reality entirely.
- Infrastructure proximity as a genuine value driver, not just a nice-to-have — towns benefiting from new roads and transit links are outperforming for a reason.
- Due diligence as a non-negotiable step, particularly for off-plan purchases and anyone buying from outside the country.
- Management quality, especially for short-let and serviced apartment investments, matters as much as the property itself.
- Realistic expectations for prime Nairobi apartments in the short term — a correction in an oversupplied segment isn't necessarily a crisis, but it does mean pricing power has shifted toward buyers and tenants for now.
The Bottom Line
Kenya doesn't have one property market in 2026 — it has several, moving in different directions at once. Prime Nairobi apartments are working through an oversupply correction. Satellite towns are riding an infrastructure-driven boom, though the easiest gains may be tapering in some spots. Diaspora capital keeps flowing in, just more cautiously than before. And off-plan investment keeps posting strong returns for buyers willing to do the legwork on developer credibility. None of that fits neatly into a single headline — which is exactly why "location, location, location" has never been more literally true than it is right now.
Frequently Asked Questions
Why are Nairobi apartment prices falling in some areas? Specific sub-markets — Westlands, Upper Hill, and parts of Kilimani — have seen apartment oversupply, pushing prices down roughly 7–11% even as the national average price index rises around 7.8%.
Which Kenyan towns are seeing the strongest property price growth? Satellite towns around Nairobi, benefiting from road and connectivity upgrades, have posted growth of around 15%, outperforming several prime Nairobi suburbs.
How much do Kenyan diaspora remittances contribute to real estate? Diaspora remittances reached a record USD 5.08 billion in the year to June 2025, projected to rise to about USD 5.24 billion in 2026, with a significant portion flowing into property purchases.
Is off-plan property still a good investment in Kenya? It can be — an analysis of eight prime off-plan developments found average returns of around 18% in 2025 — but developer delays, quality issues, and fraud remain real risks, making due diligence through platforms like Ardhisasa essential.
What is the average rental yield in Kenya right now? Around 7.4% nationally, though this varies significantly by location and property type.
Is Nairobi still a good place to invest in property? It depends heavily on the specific sub-market. Oversupplied prime apartment segments are correcting, while well-located, well-managed properties and satellite towns tied to infrastructure growth continue to perform strongly